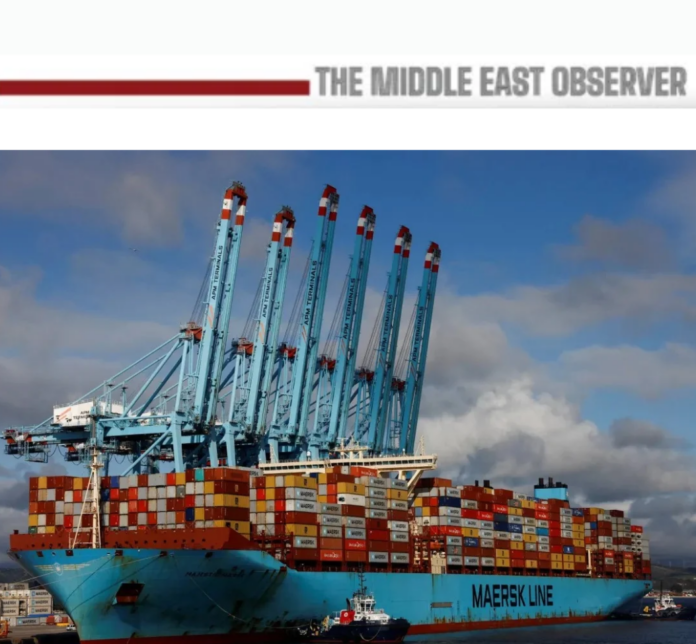
Nearly half of container ships arrive late as Asian port congestion drives up freight costs, while the return of major carriers to the Suez Canal begins to transform global shipping capacity.
Global container shipping remains under severe pressure, with only 50.6% of vessels arriving on schedule in September, while nearly two-thirds of Asia–Europe container capacity has returned to Red Sea–Suez routing, signalling a major shift in international shipping operations and freight economics.
The latest Sea-Intelligence report, released on October 28, showed reliability recovering marginally from 49.9% in August, the lowest since September 2022, but remaining far below May’s 64.5%. Late-arriving vessels averaged 6.65 days behind schedule, against 6.81 days in August. None of the world’s 13 largest carriers recorded a year-on-year improvement.
Asian port congestion remains the principal source of disruption. Regional reliability collapsed to 32.3% in August, with China’s performance falling to 23.9%. Shanghai and Ningbo recorded particularly severe declines, with just 12.2% and 16.9% of vessels arriving on time, respectively. Although congestion has begun easing at major Chinese ports, backlogs and vessel bunching continue to disrupt shipping schedules.
Freight rates are rising despite the gradual restoration of shorter shipping routes. Freightos data released on October 28 showed Asia–US East Coast rates climbing 9% to $10,565 per 40-foot container, while West Coast rates increased 3% to $8,368. Asia–Mediterranean rates rose 8% to $4,252, and Asia–Northern Europe rates gained 3% to $3,551. Separately, Drewry’s global World Container Index reached $4,585 on October 22, its highest level in 15 weeks.
The increases reflect continuing congestion, cancelled sailings and carrier pricing strategies despite softer demand on some routes. Freight forwarders are already reporting discounts, raising doubts over whether further planned November increases can be sustained.
The most consequential structural development is the accelerating return to the Suez Canal. Alphaliner estimates, cited by Freightos on October 28, indicate that nearly two-thirds of Asia–Europe container capacity has resumed Red Sea–Suez routing. Maersk and Hapag-Lloyd are progressively restoring services previously diverted around Africa’s Cape of Good Hope.
For Egypt, the recovery is already measurable. According to the Suez Canal Authority, Maersk’s canal transits increased from 146 to 276 vessels during January–September 2026, while their combined net tonnage climbed from 7 million to 23.3 million tonnes.
Further network changes scheduled for November will introduce new calls at Port Said and Damietta, while a direct Northern Europe–Jeddah connection is planned for December. Maersk aims to restore its full Suez network by March 2027, subject to regional security and operational conditions.
The shift carries opposing economic consequences. Shorter Suez voyages reduce fuel consumption, accelerate cargo deliveries and release vessel capacity previously absorbed by longer African diversions. This could eventually pressure freight rates and shipping profits, even as congestion and capacity restrictions currently support higher prices.
For manufacturers and consumers, the immediate challenge remains unpredictable deliveries and elevated transport costs. For shipping companies, the next risk could be surplus capacity as disruptions ease. For Egypt, the opportunity is to convert returning Suez traffic into lasting gains in canal revenues, port activity and international logistics.
Related News:
- Maersk Targets Full Return to Suez Canal by March 2027
- Hapag-Lloyd Eyes More Suez Canal Services in Phased Return