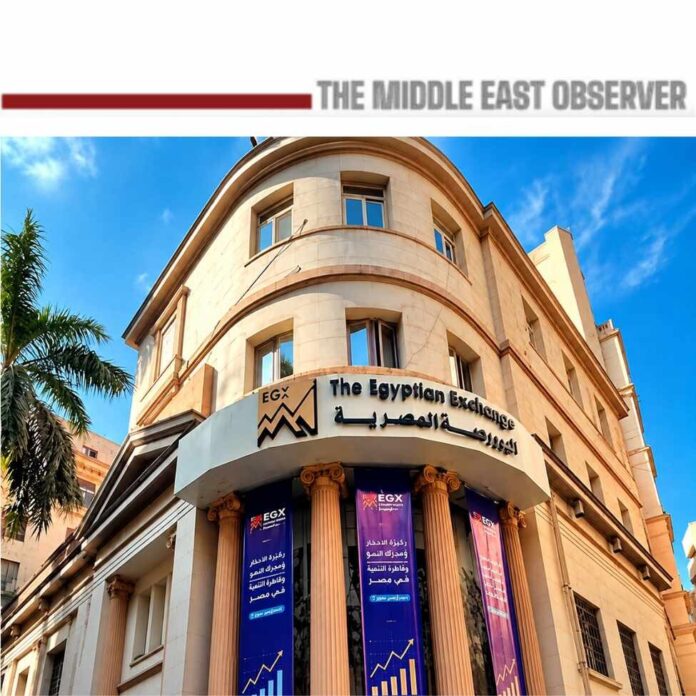
CAIRO — Egyptian institutions reversed from buyers to sellers on Tuesday, Oct. 6, as the stock-market recovery weakened for a second session, while Arab and foreign investors sharply increased their purchases of short-term government debt.
The EGX30 fell 0.48% to 53,298.14, the EGX70 EWI declined 0.68% to 19,642.65 and the EGX100 EWI lost 0.69% to 25,953.13. Market capitalisation fell about EGP25.7bn to EGP 4.213 tn, while equity trading value reached approximately EGP9.1bn on volume of 2.3bn shares.
Institutions Reverse as EGX Falls Again
Egyptians remained the sole nationality group of net equity buyers, purchasing approximately EGP208.1mn, against foreign selling of EGP142.7mn and Arab selling of EGP65.4mn.
But the aggregate Egyptian figure concealed Tuesday’s most important change.
Egyptian institutions sold EGP275.4mn after buying roughly EGP158mn on Monday — a swing of more than EGP430mn in a single session. Egyptian individuals absorbed the pressure with EGP483.5mn of net purchases, while foreign institutions sold another EGP148mn and Arab institutions EGP 57.7mn.
The distinction materially changes the interpretation of the recovery. Domestic institutions had moved from joining Sunday’s rally to buying Monday’s pullback; on Tuesday, they withdrew that support altogether.
Breadth Confirms the Weakening
Market breadth remained decisively negative at 63 gainers against 146 decliners, with 11 unchanged. That followed Monday’s 61:151 reading and Sunday’s exceptional 178:33 advance.
Broad participation has therefore disappeared almost as quickly as it emerged.
EGX30 nevertheless retained an important element of price resilience. The benchmark rose as high as approximately 53,709, reversed to around 53,169, then recovered partially to close at 53,298.
After twice failing to sustain moves above 54,000, 53,000 has become the immediate support test while 54,000–54,500 remains the barrier to renewed upside confirmation.
The market’s internal message is consequently more cautious than the relatively modest 0.48% benchmark decline suggests: index support survives, but breadth and institutional sponsorship have weakened simultaneously.
Offshore Demand Concentrates in T-Bills
The clearest contrast came outside equities.
Arab and foreign investors collectively recorded $251.4mn of net buying in the secondary government-debt market, up sharply from about $10.3mn on Monday. Crucially, the demand was concentrated in shorter-duration paper: the two groups bought a net $302.8mn of Treasury bills while selling $51.4mn of Treasury bonds.
That does not prove that the same investors moved directly from equities into government debt. It does show that offshore appetite for Egyptian assets diverged sharply by asset class, with high-yield short-duration sovereign exposure attracting demand while equities faced institutional selling.
The pound supplied a counter-signal, strengthening to an average EGP52.2534 buying and EGP52.3906 selling against the dollar, reversing much of Monday’s depreciation.
Separately, abundant banking-system liquidity remained evident as the CBE absorbed EGP 293.96 bn through its seven-day open-market deposit operation at 19.5%, roughly 83% more than the previous operation.
Monetary conditions remain restrictive: the CBE’s overnight deposit rate stands at 19%, lending rate at 20% and main-operation rate at 19.5%. Secondary-market T-bill yields were recently around 24–25% across several maturities, maintaining a formidable fixed-income alternative to equity risk.
Recovery Returns to Question
The sequence since late September has now changed materially.
Sunday showed recovery. Monday tested it. Tuesday weakened its internal confirmation.
EGX30 continues to defend 53,000, but two consecutive sessions of poor breadth and Tuesday’s reversal in domestic institutional flows have removed the strongest evidence that the late-September correction was finished.
A renewed recovery now requires breadth to turn materially positive, Egyptian institutions to return to the buy side and EGX30 ultimately to convert repeated attempts above 54,000 into a sustained break through 54,000–54,500.
Until then, Tuesday’s capital flows point to a clearer hierarchy of risk: Egyptian retail investors are defending equities, while institutional investors remain more cautious and offshore demand is considerably stronger for short-duration sovereign debt.
Related news:
New Administrative Capital to Host Egypt Mining Forum in September
EGX30 Slips as Broader Market Firms, Debt Outflows Pressure Pound
Read also:
El-Sisi Launches The Octagon, Charting Egypt’s Next Phase of Security and Reform
Egyptian Short Film Khufu Brings Contemporary Egyptian Storytelling to the Global Stage