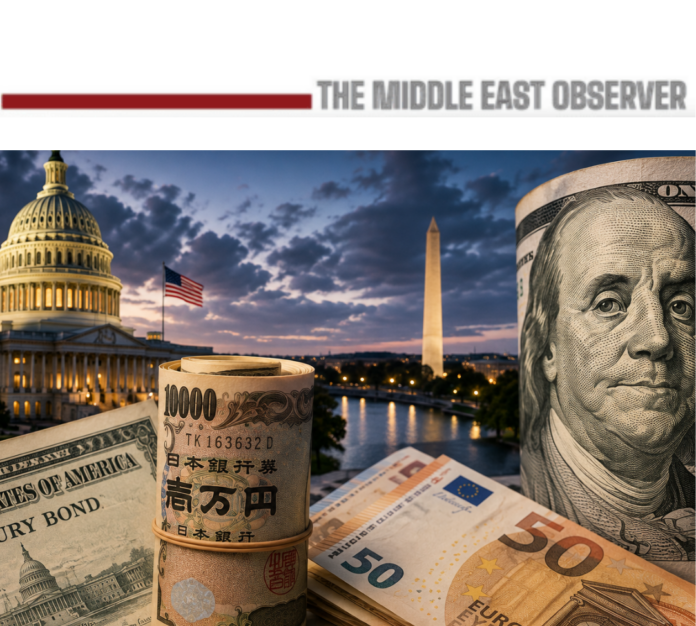
The yen’s renewed slide towards ¥160 to the dollar, less than two weeks after an extraordinary US-Japan intervention pulled it back from a four-decade low, has exposed the limits of even large-scale currency support.
Japan and the United States intervened jointly on July 31, the first coordinated effort to support the yen since 1998. The operation helped lift the currency from around ¥164 against the dollar in late July to about ¥155 earlier this month. But much of that recovery has since been surrendered.
The yen fell about 1 per cent on Monday, its worst daily performance since mid-February, before trading around ¥159.4 as markets again approached the psychologically important ¥160 threshold. Continued demand for yen-funded carry trades remains a significant source of pressure.
The reversal illustrates the fundamental problem confronting Tokyo: intervention can alter the price of a currency, but it cannot by itself eliminate the interest-rate differential that encouraged investors to sell it.
Washington’s participation nevertheless mattered. The US reportedly sold euros rather than dollars to buy yen, while Japan gained access to mechanisms capable of raising dollar liquidity against its enormous US Treasury holdings without necessarily selling the securities outright. The intervention therefore contained immediate market pressure while limiting potential disruption elsewhere in the financial system.
But the yen’s subsequent retreat demonstrates the difference between stabilising a currency and correcting the economic forces driving it.
The Rate Gap Behind the Yen
At the centre of the problem remains the wide difference between US and Japanese interest rates.
That differential supports the yen carry trade: investors borrow relatively cheaply in yen, convert the proceeds into dollars or other currencies and invest in higher-yielding assets. When volatility is low and the yield advantage remains attractive, the trade can continue even after authorities intervene.
That appears to be happening again. The Wall Street Journal reported this week that continued carry-trade demand was weighing on the yen as subdued market volatility encouraged investors to maintain risk positions.
The implication is important. Governments can buy billions of dollars’ worth of yen and punish short-term speculative positions, but as long as the return available on dollar assets remains sufficiently above comparable Japanese returns, investors retain an economic incentive to rebuild those positions.
Analysts had warned of precisely this limitation before the latest intervention. ING argued that intervention alone would struggle to produce a lasting reversal unless the underlying monetary-policy dynamics also changed. Its subsequent analysis concluded that with USD/JPY returning towards ¥160, policymakers would struggle to turn the trend without higher Japanese real interest rates or a material change in US rates.
The renewed depreciation therefore makes the central distinction increasingly clear:
Intervention can change market positioning. Interest rates change the economics of the trade.
Oil Added a Second Pressure
Interest rates were the principal financial driver, but Japan was also confronting an adverse energy shock.
As a resource-poor economy heavily dependent on imported crude oil, LNG and other fuels, Japan must finance much of its energy bill in foreign currency. Higher oil prices therefore increase its dollar requirements at precisely the moment a weaker yen makes each dollar more expensive.
Geopolitical tensions continue to keep that pressure alive. Brent crude traded around $89.46 a barrel on August 12, with prices supported by risks surrounding important Middle Eastern shipping routes and Iran’s position over the Strait of Hormuz.
Japan can consequently be squeezed from two directions:
Higher US rates → carry trades and capital flows favour dollar assets
Higher oil prices → Japanese importers require more dollars
A weaker yen then magnifies the second shock by increasing the local-currency cost of energy.
The international monetary system did not create either problem. But because interest-rate flows, commodity pricing and reserve management are all heavily connected to the dollar, separate shocks can reinforce one another through the same currency channel.
Why Washington Had Something to Lose
Japan can defend the yen by selling foreign assets and using the proceeds to purchase its currency. Given the scale of Tokyo’s reserves, however, how those operations are financed matters beyond Japan.
Tokyo remains the largest foreign holder of US government securities, with roughly $1.14tn of Treasuries.
If prolonged intervention required substantial Treasury sales, additional supply could put downward pressure on bond prices and upward pressure on US yields. Those yields influence borrowing costs across the American economy, including mortgages, corporate debt and the federal government’s own financing.
There is no evidence that Japan was preparing a large-scale Treasury liquidation, and its holdings should not be regarded as a financial weapon. Selling aggressively could damage the value of Tokyo’s remaining portfolio and disrupt markets in which Japanese institutions themselves have substantial exposure.
The issue is instead one of financial transmission: a Japanese currency problem could, under sufficiently stressed conditions, create consequences for America’s government-debt market.
Turning Treasuries Into Dollar Liquidity
The Federal Reserve’s Foreign and International Monetary Authorities Repo Facility, or FIMA, provides one way of limiting that transmission.
Instead of selling Treasury securities to raise dollars, an eligible foreign monetary authority can obtain dollar liquidity against Treasury collateral.
Treasury sale: securities → dollars → yen purchases
FIMA: Treasury collateral → dollar liquidity → yen purchases
That distinction matters because the second route can mobilise dollar liquidity without placing the underlying securities directly into the market.
US Treasury Secretary Scott Bessent has supported Japan’s use of FIMA and argued that mechanisms capable of preventing foreign financial instability from spilling into US markets serve American economic interests.
The arrangement should not, however, be interpreted as evidence of a Treasury-for-yen bargain between Washington and Tokyo. Its importance lies in providing another channel through which Japan can obtain liquidity without necessarily liquidating US securities.
Why Washington Used Euros
The US contribution addressed another side of the problem.
Rather than selling dollars to purchase yen, Washington reportedly sold euros from its foreign-exchange reserves. The transaction allowed the US to generate demand for yen without directly adding dollars to foreign-exchange markets.
The operation therefore involved two distinct mechanisms:
FIMA could reduce Japan’s potential need to sell Treasuries.
Euro-funded intervention allowed Washington to buy yen without directly selling dollars.
The ECB was reportedly caught off guard by the euro transaction. The episode demonstrated how intervention intended to stabilise one currency can quickly involve others — and how closely the world’s major reserve currencies have become interconnected.
Yet neither mechanism changes the underlying US-Japan rate differential. They improve the authorities’ capacity to manage financial stress; they do not remove the incentive that generated much of the pressure in the first place.
That distinction has become harder to ignore as the yen again approaches ¥160.
Why the UAE Didn’t Get the Same Treatment
The UAE provides a useful counter-example to the idea that ownership of US assets alone determines access to Washington’s monetary support.
Abu Dhabi reportedly explored a US dollar-liquidity backstop amid concerns that regional instability could eventually put pressure on the dirham’s dollar peg. Its circumstances differed fundamentally from Japan’s.
The yen is freely floating and has suffered substantial market-driven depreciation. The dirham is pegged at about Dh3.6725 to the dollar, meaning the UAE was seeking precautionary dollar liquidity rather than attempting to reverse a comparable collapse in a floating exchange rate.
Japan also belongs to the Federal Reserve’s small network of permanent central-bank dollar swap arrangements; the UAE does not.
The distinction demonstrates that Treasury ownership is only one consideration. Exchange-rate regimes, systemic importance, dollar-funding requirements and institutional access to the Federal Reserve’s international liquidity architecture also shape Washington’s response.
Intervention Bought Time — Not a Solution
The latest market movements provide perhaps the clearest assessment of the July intervention.
The operation worked initially.
From around ¥164, the yen strengthened to approximately ¥155, a substantial move in one of the world’s most heavily traded currency pairs.
But it did not remove the underlying incentive to sell yen.
The currency has since surrendered roughly half of that recovery and returned towards ¥160. Market participants are again discussing the possibility of official intervention should that threshold be decisively breached.
That does not mean the earlier intervention failed. Currency intervention can break disorderly market momentum, squeeze speculative positions, reduce volatility and give policymakers time.
But time is what it buys — not necessarily a new equilibrium.
Unless the interest-rate differential narrows sufficiently, repeated intervention risks becoming an increasingly expensive defence against a price signal generated by monetary policy itself.
The more durable adjustment would therefore have to come from some combination of higher Japanese rates, lower US rates, or market expectations moving convincingly towards such convergence.
That creates difficult choices on both sides. Japan cannot raise rates without considering its heavily indebted economy and domestic bond market. The Federal Reserve, meanwhile, sets rates according to US inflation and employment conditions, not the exchange-rate requirements of Japan.
And therein lies the larger international problem.
The Structural Weakness of a Single-Currency Transmission System
Japan’s predicament raises a question extending beyond the yen.
The Federal Reserve is responsible for the American economy. Its interest-rate decisions appropriately respond to US inflation, employment and financial conditions.
But because the dollar is simultaneously the world’s principal reserve, funding, settlement and commodity-pricing currency, those domestic decisions can have consequences far beyond US borders.
Japan provides a particularly clear example.
A high US interest rate relative to Japan encouraged carry trades.
A stronger dollar increased the cost of Japanese imports.
Higher oil prices increased the quantity of dollars Japan needed.
Defending the yen potentially involved dollar reserves and US Treasuries.
Washington’s response then involved euro reserves and Federal Reserve liquidity infrastructure.
A problem originating largely in an interest-rate differential consequently spread across the yen, dollar, euro, Treasury and energy markets.
Intervention could manage that chain. It could not break its first link.
From Intervention to a Multi-Currency Architecture
The yen’s renewed weakness therefore raises a more consequential question: whether the international monetary system needs additional mechanisms that reduce the extent to which the monetary policy of any single economy is transmitted through global trade and finance.
The answer need not be the replacement of the dollar.
Dollar dominance rests on formidable advantages: the depth of the US Treasury market, global banking networks, highly developed derivatives and hedging markets, convertibility and enormous pools of dollar liquidity. Replacing it abruptly — or merely substituting another dominant national currency — could exchange one concentration risk for another.
A more credible objective would be a genuinely multi-currency architecture.
Such a system could retain the dollar as its principal component while developing deeper mechanisms for reserves, trade settlement, commodity invoicing and international financing across the euro, renminbi, yen and other major currencies. Basket-based instruments could also play a greater role where commercially and institutionally practical.
The purpose would not be to eliminate currency fluctuations. No monetary architecture can remove differences in economic performance or interest rates.
Instead, diversification could provide additional shock absorbers.
An energy importer would be less exposed to a situation in which a rise in one foreign country’s interest rates simultaneously strengthens the currency required for commodity purchases, attracts capital into that country’s assets and increases pressure on domestic reserves.
This is ultimately the distinction exposed by Japan’s renewed currency weakness.
The July intervention demonstrated that governments can mobilise enormous financial resources to resist disorderly exchange-rate movements. The yen’s return towards ¥160 demonstrates something equally important: those resources cannot indefinitely overpower the interest-rate fundamentals generating the trade.
Japan’s immediate challenge remains monetary. The US-Japan rate differential must narrow — through Japanese tightening, lower US rates or changing market expectations — if the incentive behind the carry trade is to weaken sustainably. Oil prices remain an important amplifier rather than the principal cause.
But the episode leaves a broader lesson for the international monetary system. When interest rates, commodity pricing, reserves and international funding are concentrated around one dominant currency, a domestic monetary decision in one economy can propagate through countries whose economic circumstances are entirely different.
A multi-currency architecture would not prevent the next Japan. But by distributing settlement, reserve and financing exposure across several deep currency markets, it could reduce the probability that an interest-rate decision in one country sends the entire flock in the same direction.
The objective should therefore be neither to displace the dollar nor to insulate economies from market discipline, but to build a global monetary architecture with more than one effective shock absorber.
Related news:
Houthi Threat Opens Second Front in Regional Shipping Crisis
Egypt Builds a New Investment Architecture as Africa’s Top FDI Destination
Read also:
The Asymmetry Paradigm : Redefining Military Power in the Iran Conflict